Snap Finance

- 820.00 Reviews
- 4.8
- Downloads
- 500,000+
Our take on Snap Finance from Appgk
When an essential purchase cannot wait for the next payday, the difficult part is often not finding the item. It is working out how to pay for it without turning a short-term problem into a long-term one. Snap Finance is built around that moment. It is a free shopping app from Snap Finance that lets you explore a buy-now-pay-later route, with the store summary presenting it as an option that does not require traditional credit. I found it most useful when I treated it as a planning tool rather than a shortcut to spending.
The app belongs in the shopping and flexible-payment space, but that description only tells part of the story. Its real value appears during the handoff between deciding what you need, checking whether the purchase fits your situation, and completing the transaction. That handoff is where many finance-related apps become confusing. Snap Finance keeps the idea fairly direct, although the responsibility for reading the agreement and judging affordability still sits with the user.
Following a purchase from need to outcome
Starting with a real shopping problem
I would open this app with a specific purchase in mind, not simply to browse for something entertaining. A replacement appliance, necessary household item, or another planned purchase makes more sense than using it for an impulse buy. The phrase “no credit needed” may make the service feel accessible, but accessibility is not the same as affordability. A payment plan still creates an obligation, and the total cost matters just as much as the first payment.
A realistic example would be a washing machine that stops working before a household has saved enough for a replacement. I would first identify the exact model or a sensible price range, then use Snap Finance to investigate whether the purchase can be arranged through its payment process. That order is important. Starting with a fixed need helps prevent the app from becoming a reason to increase the budget simply because a payment appears manageable.
Best Parts of Snap Finance
Things to Keep in Mind About Snap Finance
The application is free to install, which lowers the barrier to checking the process. It is also marked for Everyone, so its presentation is intended to be broadly accessible. That does not mean every financial decision is suitable for every person. Younger users and anyone unfamiliar with installment agreements should involve a trusted adult and read every repayment detail before accepting anything.
Moving through the first steps
My preferred workflow is to begin by confirming the item, the retailer, and the amount I am actually trying to cover. I would then move through the app’s finance journey carefully, pausing at each screen rather than tapping through automatically. The useful question is not only “Can I complete this purchase?” but also “What will this purchase require from me afterward?”
News and Features Related to Snap Finance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The app’s appeal is that it focuses the shopping decision around a payment route instead of asking users to arrange a conventional credit card first. For someone who has limited credit history or does not want to use a card, that can remove a familiar obstacle. Still, the absence of a traditional credit requirement should not be mistaken for a guarantee that every application or purchase will proceed in the same way. The practical outcome depends on the individual application and the transaction being attempted.
I also recommend keeping the product page, the checkout information, and the finance terms visible while reviewing the offer. Those details answer different questions. The product page tells me what I am buying, checkout tells me what is due at the point of sale, and the finance agreement explains the longer commitment. Treating them as one piece of information is an easy way to miss an important difference.
Don't want to read the full review?
Understanding the handoffs
The most important part of the experience is the handoff from the app to the shopping transaction. Snap Finance is not valuable merely because it displays a payment idea; it has to connect that idea with the purchase I am trying to complete. I would expect to move between selecting an item, reviewing eligibility or payment information, and returning to the retailer’s checkout flow. Each transition deserves a quick check that the item, amount, and payment arrangement still match.
This is where I noticed the main mental workload. A shopping app normally helps me compare products, save items, or place an order. A finance-focused shopping app adds a second layer: I must track the purchase and the commitment attached to it. If I switch products halfway through, change the amount, or leave the process and return later, I would review the terms again rather than assuming the earlier information still applies.
Screenshots
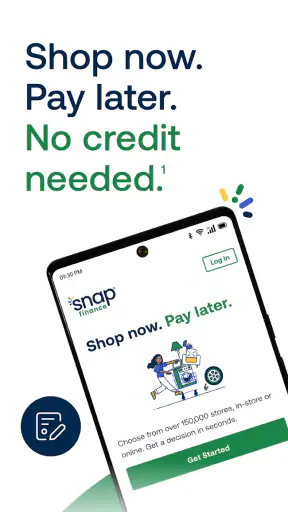
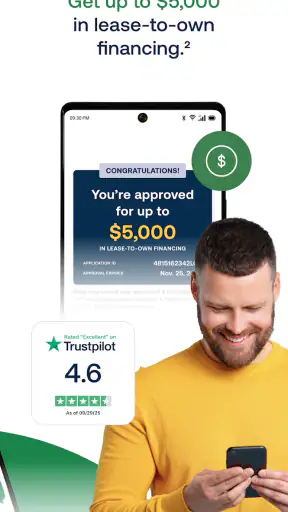
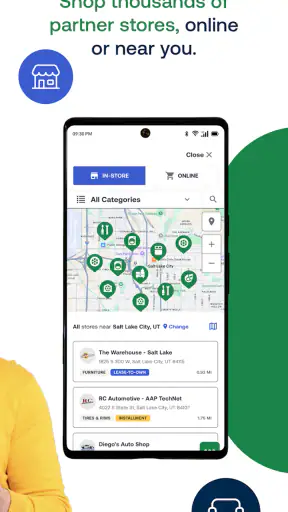
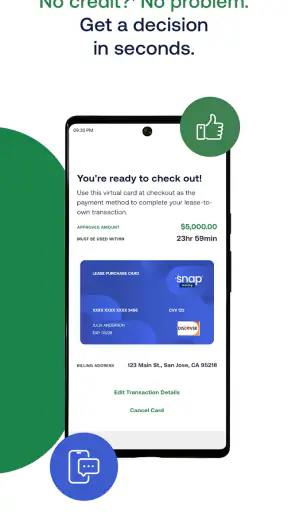
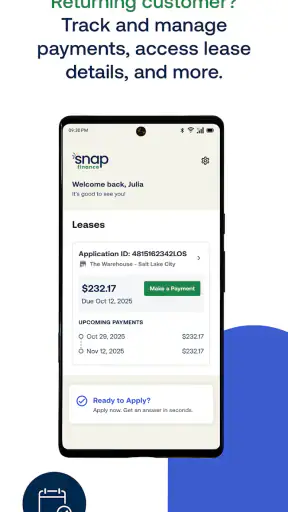
That habit is especially useful for purchases with optional extras. Delivery, installation, accessories, warranties, or a more expensive model can quietly change the amount being financed. I would decide which extras are genuinely necessary before completing the handoff. A payment plan can make a small upgrade look harmless when the overall commitment is the more important figure.
Another practical tip is to save the agreement details somewhere I can find them later, using whatever confirmation or account information the app provides. I would not rely on memory, a screenshot of a single payment, or the retailer’s product listing alone. If I need to check a due date, return a product, or ask for help, having the complete transaction context makes that conversation easier.
What the result feels like
If the process works for the intended purchase, the result is straightforward: I can obtain the item now and manage the cost through the agreed arrangement instead of paying the entire amount immediately. That can be meaningful in an urgent household situation. The app’s strongest practical benefit is therefore timing. It may help bridge the gap between a necessary purchase and the day when paying in full becomes realistic.
That benefit needs to be judged against the full commitment, not just the convenience of receiving the item. I would compare the scheduled payments with my ordinary monthly expenses and leave room for bills that are not visible during checkout. A plan that fits only when everything goes perfectly is not a comfortable plan. The best use case is one where the purchase is genuinely needed, the repayment schedule is clear, and the future payments remain manageable without relying on another borrowing decision.
Snap Finance has attracted a strong response on its app listing, with an average score of 4.8 from around 9.2 thousand ratings. It has also passed the half-million-install mark, which suggests that many shoppers are willing to try this particular route. Those figures give me confidence that the app is established enough to deserve consideration, but they do not replace my own reading of the agreement. A high rating can reflect ease of use while saying little about whether a payment plan is right for my budget.
Where the flow can break
The first weak point is financial judgment. The app can make the path from need to purchase feel shorter, but it cannot decide whether the purchase is wise for me. Anyone already struggling with recurring bills should be cautious. In that situation, a conventional savings plan, a lower-cost item, help from a trusted person, or a direct conversation with the retailer may be safer than adding another scheduled obligation.
The second weak point is comparison. A buy-now-pay-later route may appear simpler than a credit card or a retailer’s own financing, yet “simpler” does not automatically mean cheaper or more flexible. I would compare the total amount payable, the timing of installments, and what happens if circumstances change. If a bank or retailer offers clearer terms for the same purchase, that alternative may be better even if Snap Finance is faster to start.
The third weak point is a change of plan after approval or checkout. Products go out of stock, a different model becomes necessary, or a return becomes unavoidable. That is when I would stop and verify the correct process instead of assuming that canceling the order automatically cancels every related financial step. The shopping side and the payment side are connected, but they are not always the same conversation.
There is also a human-factors issue: installment payments can make a high total feel psychologically smaller. I found it helpful to write down the full purchase amount before beginning and then compare it with the repayment schedule afterward. That simple two-column check exposes whether the plan is helping with timing or encouraging a purchase I would not otherwise make.
Who will get the most from it
I see the clearest fit for shoppers who have a defined essential purchase, need an alternative to paying in full immediately, and are comfortable taking responsibility for a finance agreement. It may also appeal to people who do not want to use a credit card or who are looking for a route that does not depend on traditional credit in the usual way.
The app is less suitable for someone browsing without a budget, chasing a nonessential upgrade, or hoping that a small-looking installment will hide an unaffordable total. It is also not my first choice for a purchase that can wait until I have saved the money. In that case, saving avoids the extra complexity of managing a payment arrangement and leaves more room to change my mind.
For users who need detailed budgeting, spending categories, bill reminders, or a broad view of several accounts, a dedicated budgeting app would probably be more useful. Snap Finance has a narrower job: connecting shopping with a financing option. For product discovery, a retailer’s app may offer a better catalog. For comparing borrowing costs across providers, a neutral financial comparison service may provide a wider view. I would use Snap Finance when its specific payment path matches the purchase, not as my only money-management tool.
Small habits that improve the experience
My first recommendation is to calculate affordability before opening the checkout flow. Include existing subscriptions, utilities, transport, food, and irregular expenses rather than judging the plan against spare cash from one unusually good month. This reduces the chance that the app’s convenience will lead the decision.
Second, separate the product decision from the payment decision. Choose the item because it meets the need, then inspect how the payment arrangement changes the cost and timing. If the only reason I prefer a more expensive product is that its installment looks close to the cheaper one, I would step back and reconsider.
Third, keep a record of the final agreement and the retailer’s order details together. That is particularly useful when the purchase involves delivery, a return, or a warranty issue. It creates a clear trail showing what was ordered and which payment arrangement was connected to it, rather than forcing me to reconstruct the transaction later.
Fourth, treat any interruption as a reason to verify, not repeat. If the app closes, the retailer page changes, or I am unsure whether an application went through, I would check the account or confirmation information before starting again. Duplicate attempts can create unnecessary confusion, especially when a purchase and a finance application are moving through separate stages.
Everyday usability and maturity
Snap Finance was released on March 29, 2023, and the current Android version is 2.2.11632. It supports Android 7.0 and later, so people using older but still compatible Android phones may be able to access it without upgrading their device. I appreciate that this keeps the technical entry point relatively broad, although a compatible operating system does not guarantee that every retailer or transaction will feel identical.
The developer is Snap Finance, which makes the relationship between the app and the financing service easy to understand. That clarity matters in a purchase workflow: I know I am not dealing with an unrelated shopping catalog that merely displays payment advertisements. At the same time, I would still read the retailer’s checkout information and the agreement itself, because the developer’s identity does not remove the need to understand the specific transaction.
In day-to-day use, I would judge the app less by how quickly I reach a payment screen and more by how clearly I can retrace the decision afterward. A good finance workflow should leave me knowing what I bought, what I agreed to, and what I need to do next. Snap Finance can support that process, but only when I slow down at the points where shopping convenience and financial commitment meet.
My recommendation after following the full workflow
Snap Finance is best used as a deliberate bridge, not as permission to spend. I would recommend it to a shopper facing a real, time-sensitive purchase who has checked the total cost and can comfortably handle the agreed payments. Its free access, focused purpose, and alternative approach to traditional credit make it worth considering, particularly when paying in full today is the main obstacle.
I would not recommend opening it first for entertainment purchases, uncertain budgets, or situations where existing repayments are already difficult. In those cases, the app may solve the immediate shopping problem while making the broader money problem harder. A cheaper product, saving first, or a more transparent alternative may be the better outcome.
My final view is positive but careful. The app gives a practical route from a specific need to a completed purchase, and its broad Android compatibility and strong user response make it approachable. The real test comes after checkout, when the item is no longer exciting and the payments still remain. If I use it with a written budget, verify each handoff, and judge the full agreement rather than the smallest payment shown, it can be a useful shopping companion. If I cannot do those checks, I would skip the financing route and choose an option that keeps the purchase simpler.
Snap Finance FAQ
What is Snap Finance, and how does it work?
Snap Finance is a point-of-sale financing service that allows eligible shoppers to apply for payment options when purchasing products from participating retailers. Instead of paying the full amount immediately, you may receive a lease-to-own or financing offer, depending on your application and location. The app or website generally helps you manage applications, payments, account details, and available purchase information.
Is Snap Finance available to everyone, and what are the eligibility requirements?
Approval is not guaranteed, and eligibility can depend on factors such as your age, residence, income, banking information, identity verification, and the retailer involved. Snap Finance may consider more than a traditional credit score, but that does not mean every applicant will qualify. Requirements and availability can vary by state or region, so review the official terms before submitting an application.
How much does Snap Finance cost, and are there additional fees?
The total cost depends on the offer you receive, the purchase amount, the payment schedule, and whether the agreement is a lease-to-own arrangement or another financing product. Some offers may include fees, higher effective costs, or an early-purchase option. Before accepting, carefully check the agreement for payment amounts, dates, total ownership cost, late charges, and other applicable terms.
Can I use Snap Finance for any purchase or retailer?
Snap Finance is not universally accepted. You can generally use it only with participating merchants and for products or services that meet the provider’s rules. A retailer may also set its own minimum purchase amount, excluded products, or approval conditions. Confirm that the store is an authorized partner and that your intended purchase qualifies before relying on Snap Finance at checkout.
How do I manage payments and protect my personal information in the Snap Finance app?
After opening an account, you should be able to review payment schedules, account balances, transaction details, and available payment methods through the official app or online account. Use only the legitimate app-store listing or official website, create a strong unique password, and avoid sharing verification codes. Monitor statements regularly, enable available security features, and contact official support promptly about suspicious activity or payment errors.